The Short Answer
On September 16, the Federal Reserve raised rates for the first time since 2023. That doesn’t change whether your company can be sold. It changes how buyers pay for it and which buyers can compete. Expect more earnouts, seller notes, and rollover equity, and fewer leveraged buyers at the table. The fix isn’t waiting for a better market. It’s making your earnings easy for a lender to believe.
One of the questions I’ve heard most from owners this year is, “Should I wait for a better market before I sell?” Plenty of others haven’t asked it out loud, but they’ve been thinking about it. And it made sense. Nearly every 2026 outlook pointed to easing money and cheaper debt in the back half of the year.
Most owners weren’t really thinking about interest rates, though. They were thinking about a better market. Until last week, those were the same bet.
Then the Fed raised its benchmark rate a quarter point to a range of 3.75% to 4.00%. The vote was unanimous, and the committee’s own projections point to another increase before year end. The 10-year Treasury is near its highest level in 19 years.
So, what does that mean if you’re planning to sell in 2027? Let’s take a look at the pool of buyers.
Private equity is feeling it first
Rate hikes hit the heaviest borrowers first. Private equity is having its worst fundraising year since at least 2020, raising $211.9 billion through September 11 compared to $334.4 billion for all of last year.
Meanwhile, the lower middle market is busy. Axial counted a record 3,523 deals coming to market in Q2 2026, and 87% of dealmakers expect activity to hold steady or grow through year end. Only 3% expect a decline. (We broke down more of that data in What the 2H 2026 M&A Market Means for Sellers.)
In other words, deals are still getting done. The real question is on what terms.
Buyers won’t cut your price. They’ll change how you get paid.
This is the part most owners miss. When debt gets more expensive, a buyer rarely lowers the multiple they quoted you. Instead, they change when, and whether, you actually get paid.
It’s already happening. Earnouts now show up in 29% of lower middle market deals and in 35% of deals under $25 million. All-cash deals fell to 51% in 2025, the lowest share in four years. And those numbers are from before this hike.
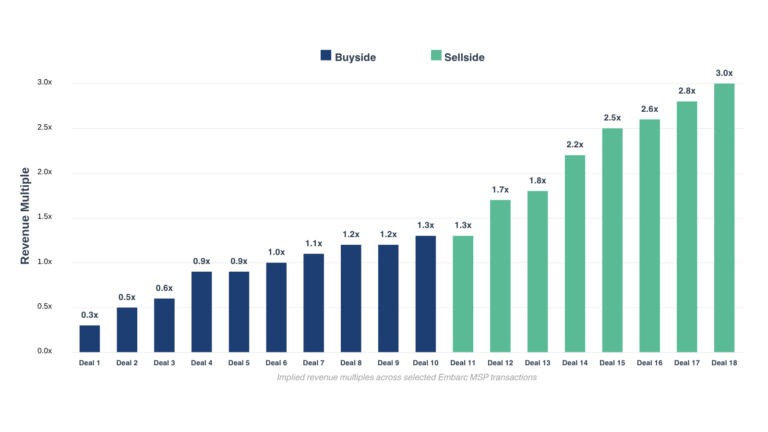
We recently ran a process for a manufacturing business that was highly profitable with strong organic growth momentum. Unsurprisingly, we received a lot of interest with over a dozen bids. The top 4 bidders all had a premium multiple valuation. The difference was structure. Some had earn-outs and some required the seller to roll equity. Only one was all cash. M&A negotiations are not just about headline valuations. Structure often determines what the seller keeps.
Two offers with the same headline price can pay out very differently. Comparing offers on the headline number alone is always a mistake. Now it’s a much more expensive one.
Leveraged buyers are the first to drop out
Not every buyer feels a rate hike the same way. Strategic buyers with cash on hand barely notice, and they actually get more competitive when leverage gets pricey. PE platforms still need to deploy capital, but you’ll see the pressure manifest in how they structure deals. Independent sponsors and searchers, who raise money deal by deal, feel it most.
Here’s why that matters to you. At higher rates, the same EBITDA supports less debt. Lenders have less room for uncertainty, so numbers in your books that are difficult to verify come straight out of what a buyer can borrow. If your earnings are easy to underwrite, every kind of buyer stays in the room. If they aren’t, the leveraged buyers leave first.
Steps you can take in the next 90 days to improve enterprise value
In a recent Axial survey, valuation gaps were the top reason deals fell apart in the first half of 2026, according to 57% of dealmakers surveyed. This is up from 28% of survey responses in 2025. Deals aren’t dying on diligence surprises or macro fear. They’re dying because buyers and sellers can’t agree on price. The way to close that gap is to make your valuation easy to support.
- Make your reporting match your story. Close monthly on accrual with consistent cutoffs. A great narrative gets a buyer interested. Verifiable numbers let them act on it. Not sure where you stand? Start with our exit-ready financial checklist.
- Get a Quality of Earnings (QofE) done now. Just because you have an addback in your Excel spreadsheet does not mean a lender will give credit for it. An addback a lender won’t credit simply shrinks what a buyer can borrow. A Quality of Earnings seeks to identify all of the potential addbacks, far beyond simply adding back owner’s salary and personal expenses. Furthermore, the QofE substantiates each addback so the lender can underwrite it with confidence. Yes, the buyer will do a QofE as well, but they are not in the business of maximizing your EBITDA, that’s the seller’s job.
- Reduce owner dependency and customer concentration. Both of these factors get modeled as risk, and both are fixable with lead time.
- Enhance the financial narrative. Clean books are table stakes for a strong exit. Track and manage key metrics like retention / repeat purchase, marketing efficiency metrics, sales pipeline metrics etc. All of these reinforce the financial narrative that buyers and lenders can underwrite.
Nothing about last week made a good company harder to sell. It made an unprepared one harder to finance. Closing that gap takes about two quarters of work, and you still have time to do it.
Thinking about selling your business in 2027? See where you stand with our Diligence Readiness Assessment.
FAQs
Should I wait for rates to come down before selling?
The Fed is signaling another increase this year, not a cut. Waiting on the market means betting against that. Waiting to improve your business is a different decision, and it’s the one you control.
Does a rate hike lower my multiple?
Not directly. Nearly two-thirds of lower middle market dealmakers expect multiples to stay stable. What changes is how much of that multiple you get in cash at closing.
How long does a sale take?
Typically, six to twelve months, depending on how prepared you are. Working backward from a 2027 close, your starting line is now!
Planning to sell your business in 2027?
Schedule a free consultation