One of the most common questions I get from business owners is some version of this: “I’m thinking about selling in three to five years. What should I be doing now to get the most value?”
It’s the right question, and three to five years is the right window. That’s enough time to make changes that actually show up in your numbers, and to build a track record a buyer will believe.
The good news is that the answer isn’t complicated. Your outcome comes down to three things, and each one has a lever you can pull.
Quick Answer
Most businesses are valued at EBITDA times a multiple, and what you take home is that value minus taxes. So there are three levers. Increase your EBITDA by documenting every legitimate adjustment with a seller’s Quality of Earnings. Earn a higher multiple with financial planning and analysis that backs your growth story with metrics and a credible forecast. And keep more of the proceeds through tax planning, such as Qualified Small Business Stock (QSBS), which can take years to set up.
In this article
- What determines what my business is worth?
- Lever 1: How do I increase my EBITDA?
- Lever 2: How do I earn a higher multiple?
- Lever 3: How do I keep more after taxes?
- Which lever should I start with?
- Frequently asked questions
What determines what my business is worth?
For most established businesses, the valuation starts with a simple equation:
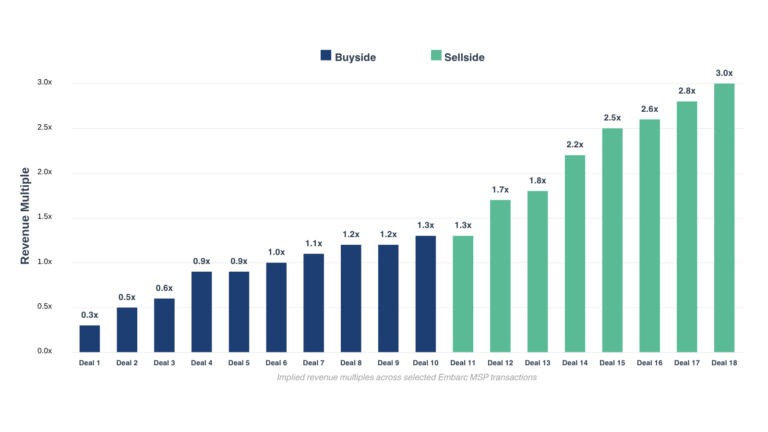
Enterprise value = EBITDA × multiple
Then there’s the part owners often forget until the end: taxes. What you actually keep is the value of the deal minus what you owe on it.
Definition: EBITDA multiple. The number a buyer multiplies your earnings by to arrive at a valuation. It reflects how confident the buyer is in your future earnings. More growth and less risk generally mean a higher multiple.
That gives you three places to focus. You can increase the EBITDA, increase the multiple, and reduce the taxes. Each one has a different tool, and each one takes a different amount of lead time.
Lever 1: How do I increase my EBITDA?
The most direct way is a seller’s Quality of Earnings (QofE). It’s the single highest-ROI investment I know of before a sale.
After you sign a letter of intent, the buyer will run their own QofE. They’ll go through roughly three years of monthly financials and separate what’s recurring from what’s one-time, non-recurring, or tied to the current owner. The result is an adjusted EBITDA, and that’s the number they put the multiple on.
The buyer’s analysis is built to protect the buyer. A seller’s QofE makes sure every legitimate adjustment in your favor is found, documented, and defended, and it surfaces the negative ones before they become a reason to renegotiate.
The math is what makes it worth it. Every dollar of adjustment is worth the multiple. At 8 times EBITDA, $10,000 in documented adjustments adds $80,000 in value. It’s not unusual to find $100,000 or more.
And this isn’t only for companies with messy books. Even clean, well-run companies have adjustments. A QofE isn’t about fixing your accounting. It’s about advocating for what your business really earns.
For more on how a QofE works, see Why Every M&A Deal Needs a Quality of Earnings Assessment and How a Preemptive Quality of Earnings Review Can Maximize Deal Value.
Lever 2: How do I earn a higher multiple?
With finance, not just accounting. Accounting tells a buyer what happened. Finance tells them why, and what happens next.
There’s an old line in sales: facts tell, stories sell. Buyers pay for a story they believe. But a story only works if it’s backed by numbers. That’s where financial planning and analysis (FP&A) comes in.
A few examples of the metrics that turn a story into evidence:
- Customer concentration. If no single customer is more than a small share of revenue, you can show the buyer that losing one won’t sink the business.
- Showing that customers stay, year after year, makes future revenue more predictable.
- Net revenue expansion. If existing customers spend more over time, broken out by the year they signed, the buyer can see growth built into the base you already have.
The other piece is the forecast. A buyer’s model is only as good as the inputs, and a forecast built from what drives your revenue and costs is much easier to underwrite than a plan that adds 10 percent to last year.
Here’s how the first two levers stack up, using a business with $12 million in revenue:
|
|
EBITDA |
Value at 10x |
|
Reported |
$1.4M |
$14M |
|
Adjusted after a seller’s QofE |
$2.1M |
$21M |
|
Next year’s forecast, backed by FP&A |
$2.4M |
$24M |
If a credible forecast gets a buyer to price on next year’s earnings, a 10x multiple on $2.4 million is $24 million. That’s more than 11 times this year’s adjusted EBITDA. A better-supported story effectively earned a higher multiple.
Figures are illustrative.
Lever 3: How do I keep more after taxes?
Plan for taxes years before the sale, not at the closing table. Federal taxes alone on a sale can take up to 23.8% of your gain, and some of the best strategies to reduce that need years of runway.
One of the most powerful is Qualified Small Business Stock (QSBS). Under Section 1202 of the tax code, owners of qualifying C corporation stock can exclude some or all of their federal capital gains when they sell, up to a cap.
Here’s what that can look like. Two co-founders, call them Ted and Harry, sold their company for $20 million, or $10 million each. Because they had planned for QSBS, they paid zero federal capital gains tax on the sale.
A few things owners often don’t realize:
- You may be able to qualify even if you’re not a C corp today. Many LLCs and S corps can convert, though it takes careful structuring, and the holding period starts at conversion. That’s why a three-to-five-year window matters.
- The rules recently got more generous. For stock issued after July 4, 2025, partial exclusions now start after three years, with the full exclusion at five.
- “Service businesses don’t qualify” isn’t the whole answer. Some industries are excluded, but eligibility depends on the specifics of your business.
QSBS is specialized. Work with a tax advisor who has real QSBS experience before you make any changes.
To go deeper, see Understanding Qualified Small Business Stock (QSBS) and How the One Big Beautiful Bill Affects QSBS.
Which lever should I start with?
Start with the one that needs the most lead time. Oddly enough, that’s usually the reverse of the order above.
- Taxes first. Strategies like QSBS can depend on holding periods measured in years. If there’s a structural change to make, every year you wait is a year off the clock.
- FP&A next. A buyer wants to see a track record, not a metric that started reporting last quarter. Retention and revenue expansion trends get more convincing with every year of history behind them.
- QofE closer to market. The full seller’s QofE usually comes right before you go to market. But the habits that make it strong start now: flagging one-time and owner-related expenses as they happen, and keeping your accounting consistent month to month.
If you’re building next year’s budget right now, that’s a natural place to begin. And you don’t need to know whether you’re selling to start. Every one of these levers makes the business stronger either way.
For another angle on what to avoid, see Common M&A Mistakes: 7 Reasons That Founders Leave Money on the Table.
How Embarc Advisors helps owners pull all three levers
Most firms cover one of these levers. At Embarc Advisors, our team works across all three. Our financial due diligence team prepares seller-side Quality of Earnings reports. Our CFO Services and FP&A team builds the metrics and forecasts that support your story. And on the sell side, we help you plan the structure of your exit alongside your tax advisor.
We’re also built differently from most M&A advisors. Our model is hourly-fee-based, not a percentage of your sale, so our advice isn’t tied to getting a deal done at any price.
If you’re three to five years out, now is a good time to talk.
Frequently asked questions
How are most private businesses valued when they sell?
Most established private businesses are valued as a multiple of EBITDA, usually adjusted EBITDA. The multiple depends on factors like growth, profitability, customer concentration, and how confident the buyer is in future earnings.
How far in advance should I plan to sell my business?
Three to five years is a good window. It gives you time to build a track record in your metrics and to put tax strategies in place that may require multi-year holding periods.
What is adjusted EBITDA?
Adjusted EBITDA is reported EBITDA after removing one-time, non-recurring, and owner-related items. It’s meant to show the ongoing earning power of the business, and it’s usually the number buyers apply their multiple to.
How can I increase my business’s valuation multiple?
Buyers pay higher multiples for businesses with lower risk and more predictable growth. Strong financial planning and analysis helps by backing your growth story with metrics like retention and revenue expansion, and with a forecast built from what actually drives your results.
Can I reduce taxes when I sell my business?
Often, yes, but most strategies require planning well before the sale. Qualified Small Business Stock (QSBS) can allow owners of qualifying C corporation stock to exclude some or all federal capital gains. Work with a tax advisor experienced in QSBS to see whether it applies to you.
Planning to sell in the next few years?
Schedule a free consultation