Originally published May 28, 2025 | Updated October 30, 2026
Summary
Most founders who sell leave money on the table because of avoidable mistakes, and the more valuable the company, the more those mistakes cost. The most costly ones are starting too late, skipping a seller’s quality of earnings (QofE), accepting a market-average multiple, ignoring taxes until the LOI, hiring an advisor with misaligned incentives, and losing focus in the final weeks, when the net working capital target is set. Each one can be avoided with preparation and the right team.
The 10 mistakes at a glance
- Waiting too long to start
- Skipping the seller’s quality of earnings
- Accepting a market-average multiple on backward-looking numbers
- Failing to plan for taxes early
- Choosing an advisor with misaligned incentives
- Trying to run the deal and the business at the same time
- Being vague in the letter of intent
- Skipping diligence on the buyer’s stock
- Letting emotions drive negotiations
- Overlooking the net working capital target
Selling your business is one of the most important decisions you’ll ever make, and one of the hardest to get right. Building a business and selling one take different skill sets, and most founders have never sold a company before. As Embarc Advisors founder Jay Jung puts it:
“The more you prepare, the more you keep.” – Jay
A former Goldman Sachs investment banker and McKinsey consultant, Jay has guided founders through the M&A process for years. Because Embarc also advises buyers, including private equity firms, we see sellers’ mistakes from both sides of the table. Here are the 10 we see most often, in the order they tend to happen.
Mistake #1: Waiting too long to start
“Most business owners have never sold a business, and selling a business is like preparing for a marathon. To run a successful marathon, to complete it and have a great result, you must prepare and train.” – Jay
Founders should give themselves at least 18 to 24 months before a planned exit. That runway improves returns, reduces stress, and gives you time to see your company the way a buyer will. Think like a private equity firm. PE buyers don’t just look for revenue or EBITDA targets; they want scalable growth and clear return potential. The earlier you start, the more time you have to shape how your business is perceived and present numbers that tell the full story. As Jay puts it: “Facts tell. Stories sell.”
Mistake #2: Skipping the seller’s quality of earnings
“If you don’t do a seller’s Quality of Earnings, you don’t know what your fully loaded, maximized, adjusted EBITDA is. That’s the equivalent of selling your home without knowing the actual square footage.” – Jay
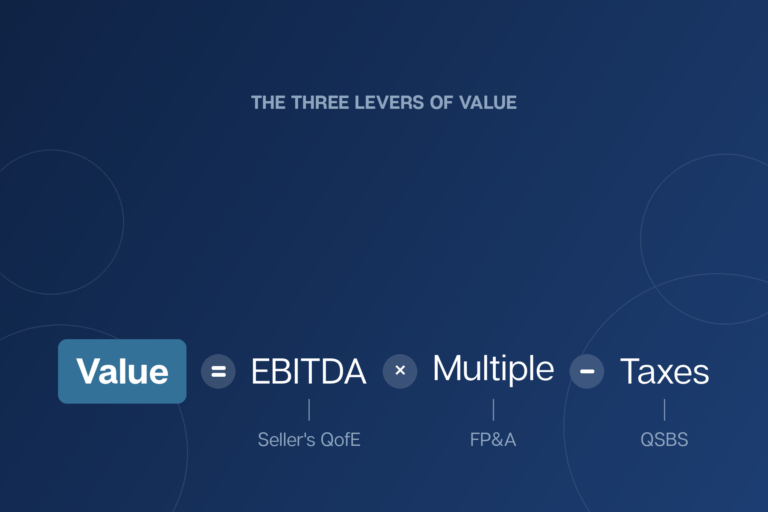
A quality of earnings (QofE) assessment strips out non-recurring items and other noise to calculate adjusted EBITDA, which shows what your business earns on a normalized basis. EBITDA isn’t a GAAP metric, and buyers will always run their own analysis. If you skip a sell-side QofE, you let the other side define your worth. The payoff can be significant. Deal value is driven by EBITDA times the multiple, minus taxes, so every dollar of supported EBITDA is worth the multiple. If a QofE finds $20,000 in additional adjustments and your company trades at 10x, that’s $200,000 in value. At Embarc, we typically find at least $100,000 in adjustments, and sometimes more than $1 million, even for companies with less than $5 million in EBITDA.
| Deal Value FormulaE (EBITDA) x M (Multiple) – T (Taxes) = NP (Net Proceeds) |
A QofE also prepares you for buyer scrutiny. When private equity raises debt to fund a deal, the amount it can borrow is typically based on a multiple of adjusted EBITDA, and its list of adjustments can run two or three pages. If your EBITDA is understated or unsupported, expect a retrade and a lower offer.
Mistake #3: Accepting a market-average multiple on backward-looking numbers
“When someone is just comfortable with that average multiple quoted in the market, they’re not really maximizing their value. You want to find the best-fit buyer; that’s who will pay a premium.” – Jay
The multiples founders hear about are medians: a safe, middle-of-the-road number. Getting above them takes strategic positioning:
- Identify the specific strategic value of your business, such as its customers, technology, talent, or geography
- Find buyers who need that value to meet their own growth goals
- Create competition among those buyers
As Jay explains, “Founders will settle for a 7x multiple because someone told them that’s the standard. We have seen those businesses trade for 10x or more with the right buyer.” The numbers you apply the multiple to matter too. Many sellers market on their last 12 months (LTM), but a growing business looks very different on forward numbers.
“When I was in investment banking, we never valued a company off backward-looking numbers. It was always a forward multiple applied to forward earnings. Don’t shortchange yourself.” – Jay
The challenge is supporting those projections. Embarc builds a bottom-up forecast from the QofE, modeled the way PE investors build their own, so buyers recognize it and have the confidence to underwrite it.
Mistake #4: Failing to plan for taxes early
“The government is effectively a third business partner you have to pay. The earlier you start planning, the more you save. If you wait until the LOI, it’s already too late.” – Jay
Founders can lose 20 to 35 percent or more of their sale proceeds to taxes. Early planning opens up strategies that disappear once a deal is underway. The biggest is often the Qualified Small Business Stock (QSBS) exclusion under IRC Section 1202, which can exclude millions in gains from federal capital gains tax for eligible owners. The rules changed in 2025, so see our QSBS guide and confirm the details with your tax advisor. Other strategies, such as a cash balance plan or a charitable remainder trust, take less time but can still save hundreds of thousands of dollars. All of them need lead time. As Jay explains, “We’ve had founders come to us with only six months left before they want to sell, and at that point, there are only a limited number of tactics that we can apply. Once the transaction process starts, your options are basically gone.”
Mistake #5: Choosing an advisor with misaligned incentives
“We choose an hourly model because it lets us give objective advice, even when it’s not what the client wants to hear. A success fee makes that nearly impossible.” – Jay
The traditional success fee sounds founder-friendly: the advisor gets paid only if the deal closes. But it rewards speed, not quality, and it does nothing to reward better terms beyond the headline price.
- Taxes: On a $10 million deal, the success fee is the same whether you pay a lot in taxes or very little, so there’s no incentive to spend extra time on a better tax structure.
- Earn-outs: Success fees are often paid on the full value of the earn-out at closing, even if the seller never hits the targets. That creates an incentive to accept a large earn-out rather than an achievable one.
- Speed over quality: Because the fee depends on closing, the model rewards getting a deal done quickly, even if that means settling for weaker terms.
Hourly advisors are paid for their time and judgment, so they’re free to give objective advice, and they’re accountable for showing how each step adds value. There’s no minimum commitment or tail period. For a full breakdown of how advisors charge, see our guide to M&A advisory fees.
Get a Sell-Side Roadmap. Download our M&A Process Guide for a step-by-step overview of the M&A sell-side process.
Mistake #6: Trying to run the deal and the business at the same time
“The number one negotiating strength that a seller has is that the business continues to perform well. If a business continues to hit it out of the park, every buyer wants to buy that company.” – Jay
Founders are tempted to stay hands-on in every part of the deal, but managing a transaction while running day-to-day operations usually means doing neither well. If performance slips, buyers see a reason to retrade, and you end up negotiating from weakness. The answer is a division of labor. Let a dedicated M&A team handle buyer outreach, diligence, and valuation work while you protect the momentum that made your company attractive. As Jay puts it, “To have the most leverage, founders should aim to deliver the best results in the last six months. If they focus on the transaction itself, they get fatigued, frustrated, and exhausted. And when you’re exhausted, you’re not going to be able to negotiate.”
Mistake #7: Being vague in the letter of intent
The letter of intent (LOI) is non-binding, but it’s the first draft of your final deal. Leaving details to “work out later” is a mistake, because the seller loses most of their negotiating power once the LOI is signed and exclusivity begins. At that point, you move from offense to defense. A detailed LOI shows the buyer is serious, clarifies terms, protects your interests, and makes diligence smoother. Ask for everything you want before you sign. For more, see Term Sheet and LOI Negotiation.
Mistake #8: Skipping diligence on the buyer’s stock
Many buyers, especially private equity platforms, ask sellers to roll over part of their proceeds into equity in the combined company. If you sell for $20 million and roll $4 million, you walk away with $16 million in cash and make a $4 million investment in the buyer. It may be your largest single investment. The price per share you roll at matters. Say the buyer’s shares triple in value by the next exit. If you rolled at $2.00 per share, your $4 million becomes $12 million. If you negotiated $1.50 per share, it becomes $16 million. Treat rollover equity like any other investment and ask for diligence information on the buyer. Buyers are sometimes surprised by the request, but in our experience they provide it every time.
Mistake #9: Letting emotions drive negotiations
“Selling is an emotional endeavor. Founders have grown their business for 5, 10, maybe 20 years, so it’s understandable they get emotional. But the biggest enemy in negotiation is emotion. The person who wins is the one who looks at everything objectively and isn’t burdened by pride, ego, or sentiment.” – Jay
A disappointing offer, a late-stage retrade, or a buyer’s lack of tact can push even the most reasonable founder to react. Taking those moments personally can derail a strong deal. A good M&A advisor acts as a buffer, absorbing difficult conversations and advocating for your best terms without the emotional weight.
Mistake #10: Overlooking the net working capital target
One of the last items negotiated is the net working capital target, often set about a week before the purchase agreement is signed. It sounds technical, but it can shift the purchase price by an estimated 2 to 5 percent or more, up or down. By then, sellers are often exhausted from diligence and let their guard down. Many founders have stories of negative working capital adjustments they didn’t fully understand until after closing. Stay focused until the very end, and make sure the target is set on terms that are fair to you.
How to avoid these mistakes
Most deal-killing errors come from the same root causes: starting late, going it alone, and losing focus at the end. The most effective protection is to bring in the right advisory team early, one with the financial analysts, QofE specialists, tax strategists, and M&A advisors to carry a deal from strategy through closing, so you can keep running the business that makes your company valuable. Learn more about our sell-side advisory.
Frequently asked questions
What is the biggest mistake founders make when selling a business?
Starting too late. Without 18 to 24 months of preparation, founders lose time to strengthen financials, complete a seller’s QofE, and plan for taxes, which are three of the biggest drivers of net proceeds.
How early should I start preparing to sell my company?
At least 18 to 24 months before your planned exit. Tax strategies in particular need lead time and are largely unavailable once the LOI is signed.
Do I need a quality of earnings report as a seller?
Yes. A seller’s QofE establishes and defends your adjusted EBITDA before buyers run their own analysis, which reduces the risk of a retrade and helps you market your true value.
What happens after I sign an LOI?
You typically enter exclusivity with that buyer and lose most of your negotiating leverage. Negotiate key terms, including structure, earn-outs, and rollover equity, before signing.
What is rollover equity?
The portion of your sale price you reinvest in the buyer’s company instead of taking cash. The price per share and the buyer’s prospects determine what it’s worth at the next exit, so it deserves its own diligence.
How does the net working capital target affect my sale price?
If the business delivers less working capital at closing than the agreed target, the purchase price is usually reduced, and if it delivers more, the price may increase. Adjustments of 2 to 5 percent or more of the price are possible.
Let’s make sure you avoid these costly mistakes in your exit.